Lenders Mortgage Insurance (LMI) is the extra cost of borrowing more than 80% of a property’s value. Some investors wait years to save a 20% deposit so they can avoid it. Others pay it and buy sooner, sometimes using the same savings to buy two properties instead of one.
Neither approach is automatically right. We break down the numbers for both, including the holding costs and downside risks that most LMI comparisons leave out.
LMI is a one-off premium charged when your loan is more than 80% of the property’s value. It protects the lender, not you, if you default.
On a $500,000 property with a 10% deposit, LMI is commonly in the range of $7,000 to $10,000. The exact cost depends on the lender and the loan size, so ask a broker for a quote.
There are two ways to pay it:
Upfront in cash. Your loan stays smaller, but you need more cash on the day.
Added to the loan. You need no extra cash now, but you borrow more and pay more interest over time. Some investors later look at refinancing or paying the debt down, depending on their lender and circumstances.
For an investment loan, LMI may be claimable over several years as a borrowing cost, so ask your accountant. First home buyers purchasing a home to live in may be able to avoid LMI through the 5% Deposit Scheme, but that scheme does not apply to investment purchases.
The Real Question Is What You Do With the Difference
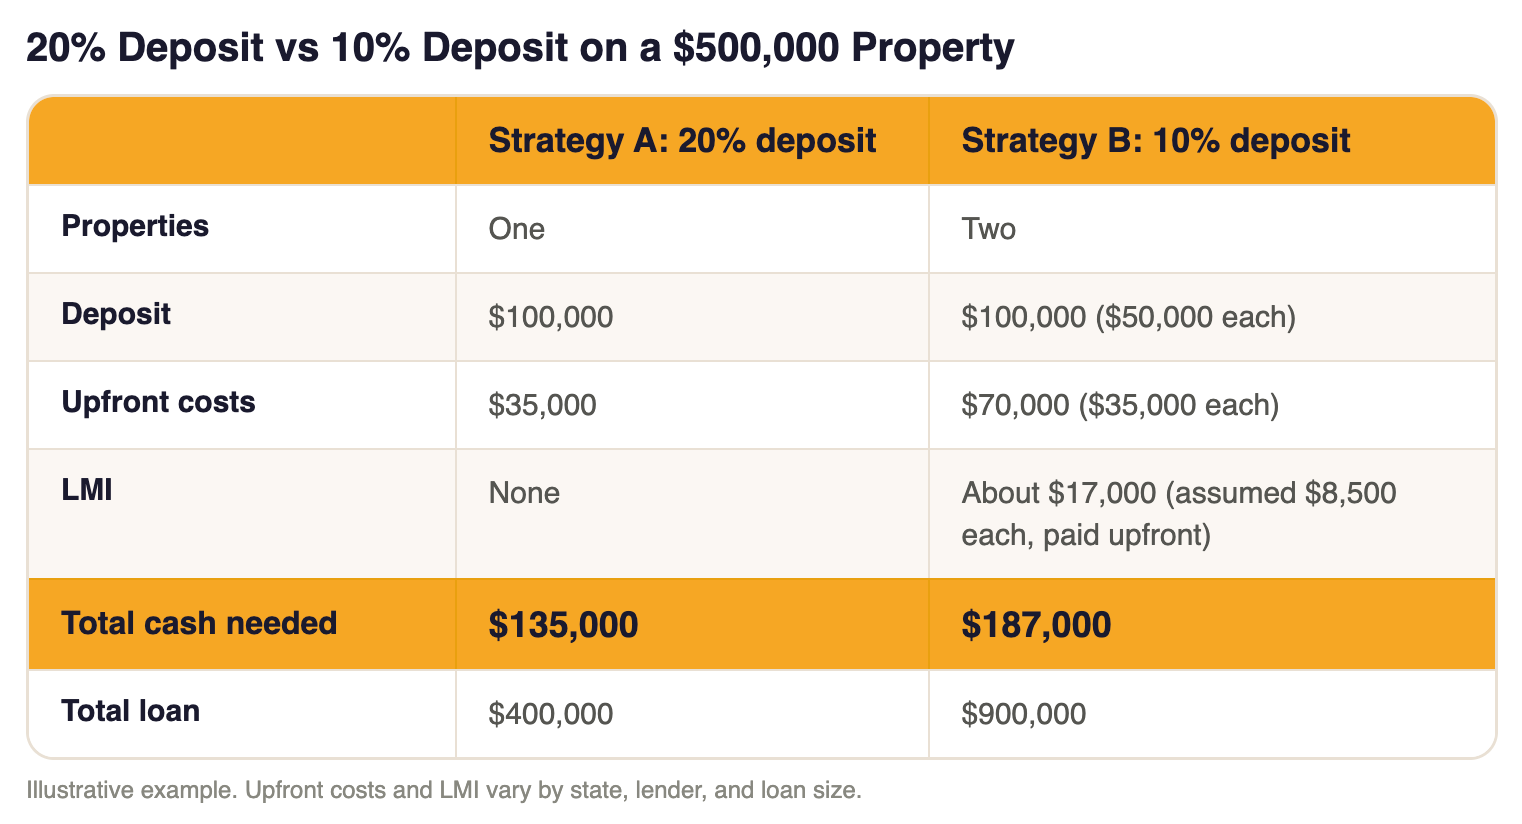
Take a $500,000 property and compare two ways of using roughly the same savings.
Strategy B is not the same amount of money. It needs about $52,000 more cash, because each property carries its own upfront costs and LMI. The $35,000 figure covers stamp duty, legal costs, inspections, and a buyers agent fee (stamp duty also varies by state).
What the Numbers Show
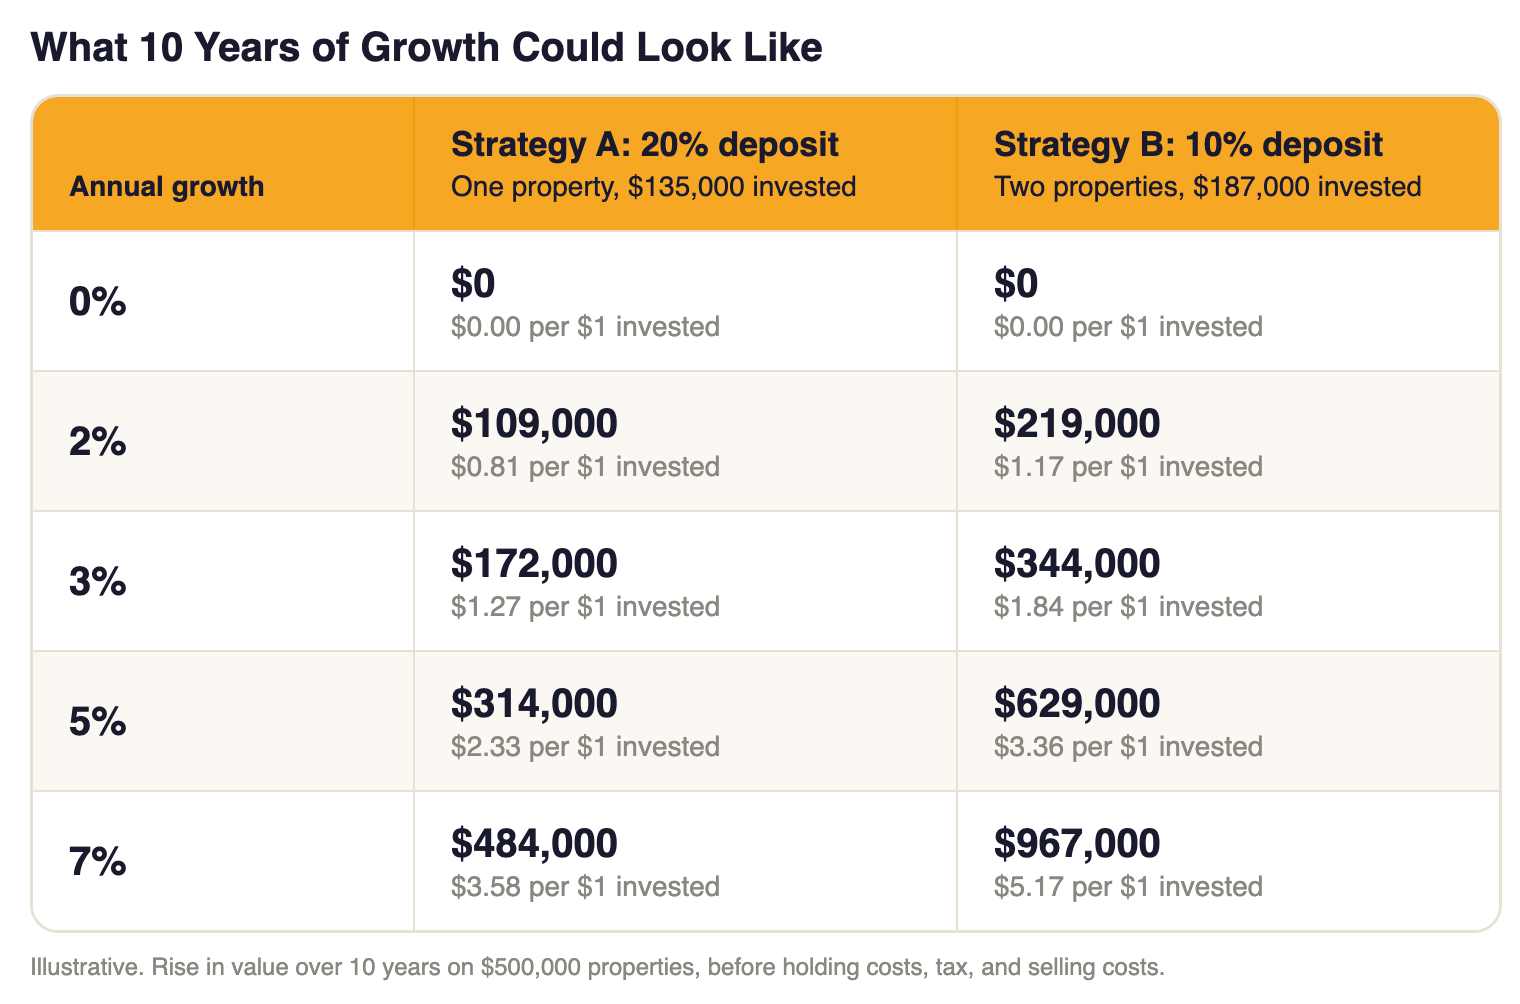
Assume both strategies are held for 10 years on interest-only loans, so the debt stays the same. The table shows the rise in property value, and how much of it you gain per dollar of cash invested.
At 5% growth, Strategy A gains about $314,000 on $135,000 invested, or $2.33 per dollar. Strategy B gains about $629,000 on $187,000, or $3.36 per dollar. In this scenario the second property does more than enough work to cover the LMI, because you control twice the value with a similar pool of savings.
Three things to keep in mind when you read this table:
It is an assumption, not a forecast. National prices are currently down 3.3% from their March 2026 peak, according to the September Home Price Index.
It is a gain on paper over ten years. It is not annual income, and it is not the same as cash-on-cash return. You can only use it by selling or borrowing against it.
It is before holding costs, tax, and selling costs. Unrealised gains are not taxed until you sell, but CGT applies when you do, and the rules change from 1 July 2027.
The table also shows the other side. At 0% growth, neither strategy gains anything and Strategy B has spent $52,000 more to get there. At 2%, gains are small relative to the cash invested.
What the Numbers Don’t Show
Holding costs
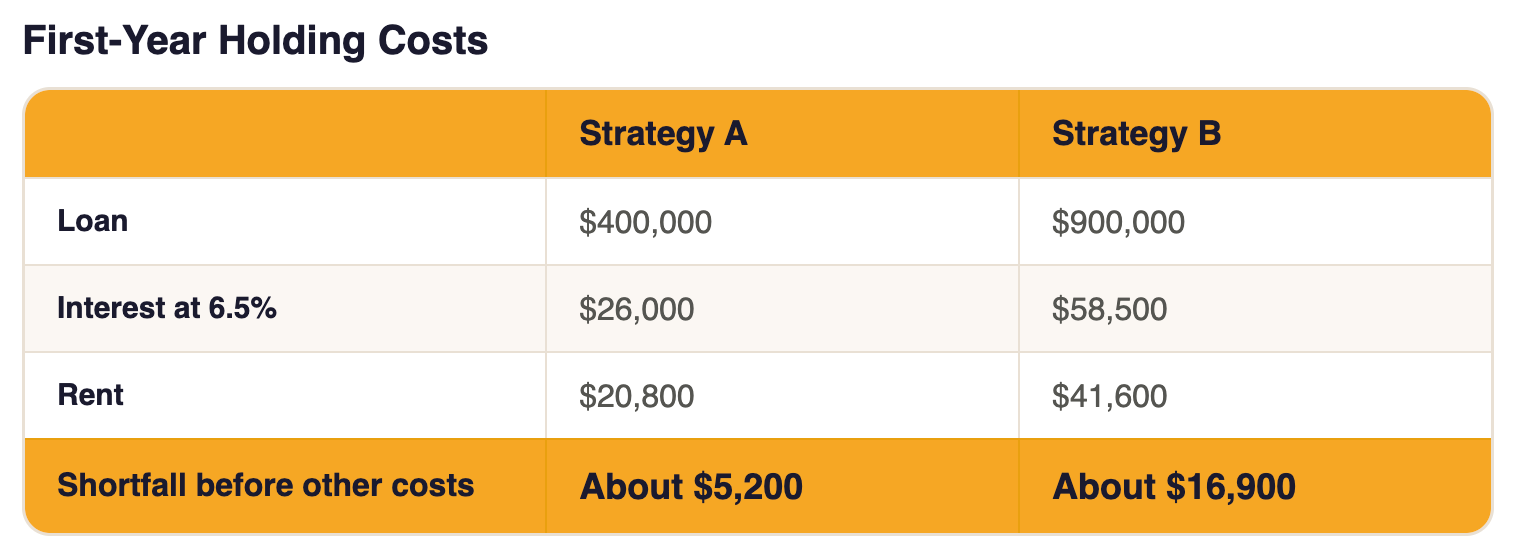
Growth is only half the picture. Here is the first-year interest bill on interest-only loans at 6.5%, with each property renting for $400 a week. These are illustrative figures.
Strategy B’s shortfall is before council rates, insurance, management fees, and maintenance. It is also real cash, because for established properties bought after 12 May 2026, losses carry forward against future property income instead of offsetting your wages. New builds keep full negative gearing.
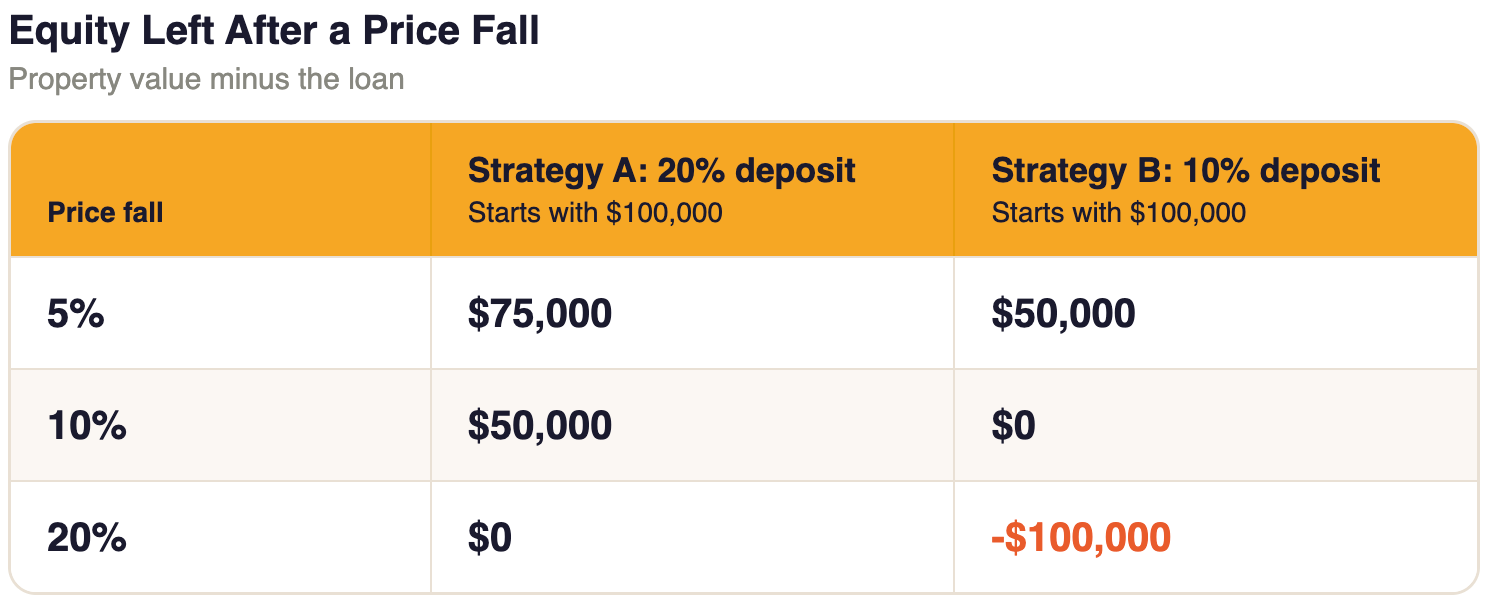
A smaller deposit leaves a thinner cushion. This table shows the equity left (value minus loan) if prices fall right after purchase, before selling costs.
Negative equity is rare at the moment. The RBA’s Financial Stability Review found that fewer than 1% of borrowers owe more than their property is worth. The borrowers most likely to be in that group are recent buyers and those with high loan-to-value ratios, which is where Strategy B starts. Negative equity does not force a sale if you can keep making repayments, but it can limit your ability to refinance or borrow again.
Debt on a Growing Asset
A loan that stays the same size gets smaller relative to an asset that grows. As a hypothetical, suppose someone borrowed $200,000 against a property 30 years ago and never paid down the principal. If that property is now worth $2 million, the same debt is a 10% loan-to-value ratio.
That is the long-term pattern behind leverage. It only works if you can keep servicing the loan, the asset grows, and you hold for long enough. Our using equity to buy an investment property blog explains how growth can fund the next purchase.
When Avoiding LMI Makes Sense
Paying 20% and avoiding LMI is often the better choice when:
Your borrowing capacity only supports one property. The extra 10% cannot buy a second property, so the LMI would be a cost with no benefit.
You want a larger cash buffer. Money sitting in an offset account can protect you through a rate rise or a vacancy.
Cash flow on two properties would be tight. If the shortfall in the holding costs table would strain you, the second property adds risk.
You are unsure about the market. A lower deposit leaves less room if prices fall.
A Middle Path
You do not have to choose between a 20% deposit and two properties. Some investors buy one property with a 10% deposit, pay the LMI, and keep the remaining $50,000 in an offset account as a buffer. They add a second property later, once their capacity and cash flow allow it.
Many investors start with one purchase and add more after seeing how holding costs and the market behave. Whatever you choose, getting started matters more than finding the perfect deposit size.
Five Questions That Can Help You Decide
Can you borrow for two properties at the assessment rate?
Can you carry both through a 1% to 2% rate rise and eight weeks of vacancy?
Will you hold three to six months of repayments as a buffer after settlement?
Are the properties in supply-constrained markets with real demand drivers?
Could you hold through a 10% price fall without selling?
If any answer is no, one property, either with 20% down or with 10% down plus an offset buffer, may be the better start.
Ready to Work Out the Right Deposit Strategy?
At Search Property, we help Australians cut through the noise and build data-driven investment strategies aligned with long-term wealth goals. Our buyers agents have helped thousands of clients build wealth through property because we focus on fundamentals, not headlines.
LMI is a one-off premium charged when you borrow more than 80% of a property’s value. You pay it, but it protects the lender if you default. You can pay it upfront or add it to the loan.
How much does LMI cost on a $550,000 property?
With a 10% deposit it is commonly around $7,000 to $10,000, but it varies by lender and loan size. A broker can give you an exact quote.
Is it better to pay LMI upfront or add it to the loan?
Paying upfront keeps your loan smaller and saves interest, but needs more cash. Adding it to the loan keeps your cash free, with a larger loan and more interest over time. The better option depends on how much cash you want to keep as a buffer.
Is it worth paying LMI to buy sooner?
It can be, if you can service the loan and the property grows. The table above shows that at 5% growth the second property outweighs the LMI, while at 0% to 2% growth it does not. Your borrowing capacity and cash buffer matter as much as the LMI itself.
Is LMI tax deductible?
For an investment loan, LMI may be claimable over several years as a borrowing cost. Confirm the treatment with your accountant.
Disclaimer: Important Notice for Readers
By reading the content provided on this blog, you acknowledge and agree to the terms outlined in this disclaimer, binding yourself to its provisions unconditionally.
This blog presents information for informational, educational, and general non-advisory purposes only. It's important for you, the reader, to understand that the information provided does not take into account your specific personal, financial, or other circumstances. Consequently, we do not offer legal, financial, investment, or taxation advice, recommendations, or guidance. Before acting upon any information from this blog, you are strongly advised to consult with an independent professional, including legal, financial, taxation, accounting, or other relevant advisors, to verify the information’s relevance to your particular situation.
The information is provided in good faith, derived from sources believed to be reliable. However, we do not guarantee the accuracy, completeness, or applicability of the information to your individual circumstances, needs, objectives, or financial situation. The information may be selective and has not been independently verified. Therefore, it should not be the sole basis for any decision-making.
We expressly disclaim any liability for errors, omissions, or inaccuracies in the information, as well as any direct or indirect losses, damages, or expenses that arise from relying on our content, regardless of the cause, including negligence or other factors. Your engagement with this blog is entirely at your own risk.
Please be aware, we do not hold an Australian Financial Services Licence as defined by section 9 of the Corporations Act 2001 (Cth), nor are we authorised to provide financial services, and we have not provided financial services to you.
Disclaimer: Search Property Pty Ltd (SP) does not provide financial or investment advice and does not hold a financial services license as defined in the Corporations Act 2001 (Cth). Any advice given by SP is general in nature and does not take into account your personal circumstances or objectives, financial situation or needs.