What High Net Worth Property Investors Do Differently
Investors with large portfolios tend to share a handful of habits. None of them are secrets. Most come down to structure, location, debt, and who they have around them.
We cover habits that show up again and again amongst experienced investors. They are common patterns, not a study, and they do not guarantee any result. You also do not need a high income to use most of them. Plenty of investors with average incomes have built portfolios of one to three properties by getting the basics right.
The way you hold a property affects your tax, your borrowing capacity, your asset protection, and your land tax. Personal name, company, trust, and SMSF each work differently, and the right one changes as your portfolio grows.
In your own name, rental income and gains are taxed at your marginal rate, which is up to 47% including the Medicare levy. A non-trading company pays a flat 30% but has no access to the CGT discount. Trusts and SMSFs have both changed in 2026. The budget introduced a 30% minimum tax on trust distributions, and a draft fix is still before parliament. Borrowing to buy residential property through an SMSF has ended for new arrangements.
No structure is best for everyone. The point is that the choice should be made on purpose, with a property-specialist accountant, before you sign a contract. Changing structure after you buy can trigger stamp duty and capital gains tax. Our investment property tax blog covers the basics.
2. They Invest Across Borders, Not Just Across the Road
Many investors only know the suburbs around where they live. They pick up the local agent’s brochure, buy nearby, and stop there.
Investors with larger portfolios tend to look wider. Each state has its own rules, including stamp duty and land tax, and those rules can change. A portfolio spread across states is less exposed to any one government’s decisions. It is also less exposed to one local market, which matters because three properties in neighbouring suburbs behave much more like one property than three.
The other reason is timing. Different markets sit at different stages of their cycle, so one that has already boomed serves a different purpose from one that is only starting to lift. The catch is that you cannot judge a market you have never visited from a listing site alone. That is where local data and an agent who works in the area matter.
3. They Separate Where They Live From Where They Invest
Rentvesting means renting where you want to live and investing where the numbers work. Instead of stretching to buy a home in an expensive suburb, you invest in a market with stronger yield or growth, and keep your lifestyle flexible.
It is not right for everyone. Renting offers less security than owning, and it affects your eligibility for first home buyer support, which generally requires that you have not owned property before. Check the current scheme rules before you buy.
It tends to make more sense where buying costs far more than renting. According to Compare the Market, mortgage repayments on a median house are 106% higher than rent in Sydney, 75% higher in Brisbane, and 66% higher in Melbourne. Our rentvesting blog explains how the strategy works, and our rent vs buy breakdown by city has the full numbers.
4. They Value Practical Experience and Outsource the Rest
Reading about push-ups is not the same as doing them. The same goes for property. Plenty of people have read the books and completed the courses. Fewer have competed for a property, negotiated a contract, or held a portfolio through a rate rise.
Investors with big portfolios usually rely on people who do this every week, and they hand over the parts they are not best placed to do. There are two common reasons. The first is time, because a full-time team can compete at a level someone doing it on the side cannot. The second is emotion. When your own money is on the line, negotiating gets personal, and putting a buffer between you and the negotiation tends to lead to better decisions.
In practice, that team usually includes a mortgage broker, a property-specialist accountant, and a buyers agent. Fees vary. Buyers agents typically charge either a percentage of 1.5% to 3% of the purchase price or a fixed fee of $15,000 to $33,000 for a full-service engagement. Check that whoever you hire is paid by you and not by developers or selling agents.
5. They Use Debt on Purpose and Plan for What It Costs
Leverage is how most investors buy more than their savings alone would allow. It does not need to be extreme. Many investors borrow 70% to 80% of a property’s value rather than 90% or 95%, and keep more of their own capital in the deal.
Debt also amplifies the cost of rate changes. On a $1 million loan, a 1% change in the interest rate is roughly $10,000 a year. On $10 million of debt it is roughly $100,000. The cash rate is now 4.6%, and lenders assess new borrowers at a rate 3 percentage points above their actual loan rate.
The long-run argument for debt is about inflation. Over many years, inflation tends to push up rents and property values while a loan stays the same size in dollars, so its real weight shrinks. That is a long-term pattern, not a promise. It only helps if you can keep paying through the years when rates rise and cash flow tightens, which is why a cash buffer of three to six months of repayments matters. Our cash flow blog breaks down the details further.
6. They Tune Out the Noise and Follow a Plan
On any given day the headlines say the market is crashing, or surging, or about to be changed by AI, a conflict overseas, or a government proposal that never arrives. Each one adds more grey to the picture.
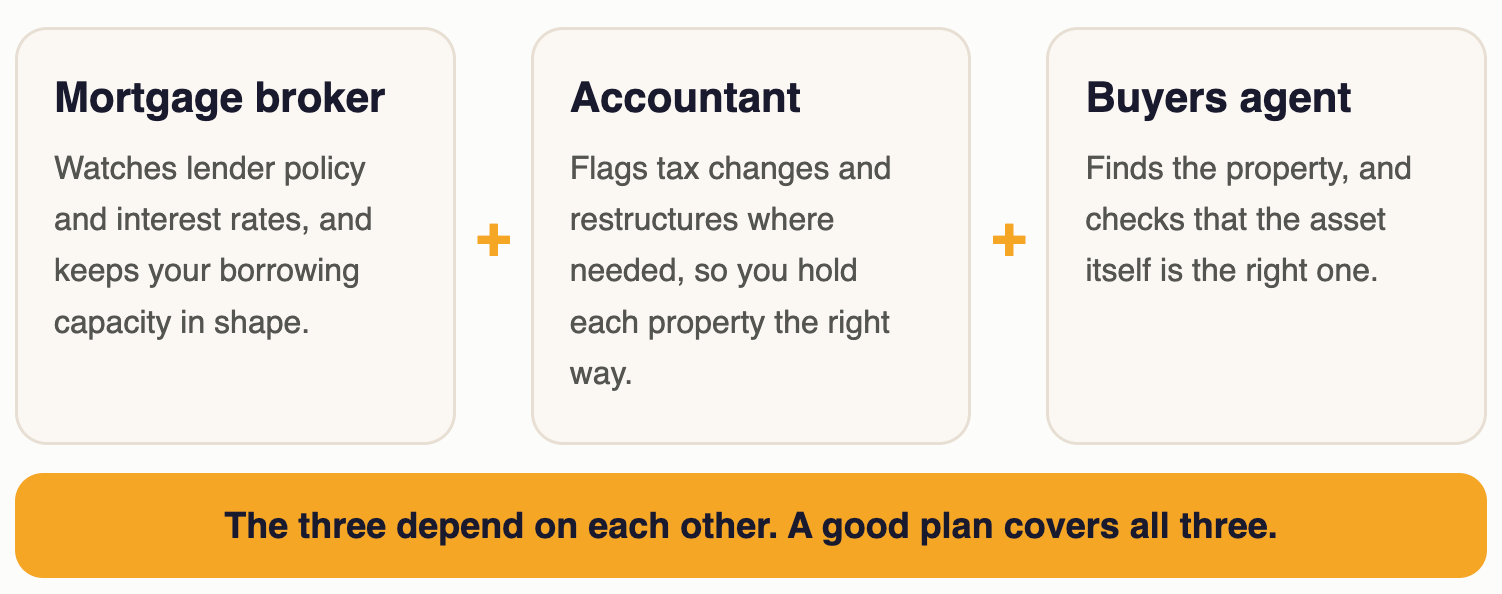
Investors with big portfolios tend to work from a plan instead. It is written down, it includes an emergency buffer, and it comes with people who review it when something changes. A broker watches lender policy and interest rates. An accountant flags tax changes and restructures where needed. A buyers agent finds the property.
These roles depend on each other. You can have the right structure and the right borrowing capacity and still buy the wrong asset. You can also buy the right asset and hold it in the wrong structure, which costs you in tax. A good plan covers all three.
How to Use This If You Are Not a High Net Worth Investor
You do not need a seven-figure income to apply the thinking.
Talk to an accountant before you buy. Settle the structure first.
Look beyond your own suburb. Compare markets on yield, growth, and supply, not postcode.
Build a buffer. Aim for three to six months of repayments before you take on the next property.
Write the plan down. A strategy gives you a way to say no to the wrong deal.
Ready to Build a Plan That Fits Your Situation?
At Search Property, we help Australians cut through the noise and build data-driven investment strategies aligned with long-term wealth goals. Our buyers agents have helped thousands of clients build wealth through property because we focus on fundamentals, not headlines.
Book a FREE investment assessment call with Search Property. We’ll look at your position, your borrowing capacity, and the strategy that fits your goals.
Frequently Asked Questions
What do high net worth property investors do differently?
In our experience they tend to choose their ownership structure on purpose, spread their investments across locations, use debt carefully, and rely on a team instead of doing everything themselves. They also follow a written plan instead of reacting to the news.
Is it better to buy in one state or several?
Spreading across states reduces your exposure to one government’s rules and one local market. It also takes more research and local knowledge, which is where a buyers agent or other adviser helps. Whether it suits you depends on your budget and goals.
Is using more debt always better?
No. Debt amplifies both gains and costs. Higher interest rates raise your repayments, and lenders assess you at a buffer above the real rate. Many investors borrow 70% to 80% of a property’s value and hold a cash buffer so they can keep holding through a difficult period.
Why would an investor outsource buying?
Time and emotion. A team that works in the market full time can often compete more effectively than someone doing it on the side, and a buffer between you and the negotiation helps you stay objective when your own money is involved.
Disclaimer: Important Notice for Readers
By reading the content provided on this blog, you acknowledge and agree to the terms outlined in this disclaimer, binding yourself to its provisions unconditionally.
This blog presents information for informational, educational, and general non-advisory purposes only. It's important for you, the reader, to understand that the information provided does not take into account your specific personal, financial, or other circumstances. Consequently, we do not offer legal, financial, investment, or taxation advice, recommendations, or guidance. Before acting upon any information from this blog, you are strongly advised to consult with an independent professional, including legal, financial, taxation, accounting, or other relevant advisors, to verify the information’s relevance to your particular situation.
The information is provided in good faith, derived from sources believed to be reliable. However, we do not guarantee the accuracy, completeness, or applicability of the information to your individual circumstances, needs, objectives, or financial situation. The information may be selective and has not been independently verified. Therefore, it should not be the sole basis for any decision-making.
We expressly disclaim any liability for errors, omissions, or inaccuracies in the information, as well as any direct or indirect losses, damages, or expenses that arise from relying on our content, regardless of the cause, including negligence or other factors. Your engagement with this blog is entirely at your own risk.
Please be aware, we do not hold an Australian Financial Services Licence as defined by section 9 of the Corporations Act 2001 (Cth), nor are we authorised to provide financial services, and we have not provided financial services to you.
Disclaimer: Search Property Pty Ltd (SP) does not provide financial or investment advice and does not hold a financial services license as defined in the Corporations Act 2001 (Cth). Any advice given by SP is general in nature and does not take into account your personal circumstances or objectives, financial situation or needs.