Positive vs Negative Gearing While Investing In Property (Explained)
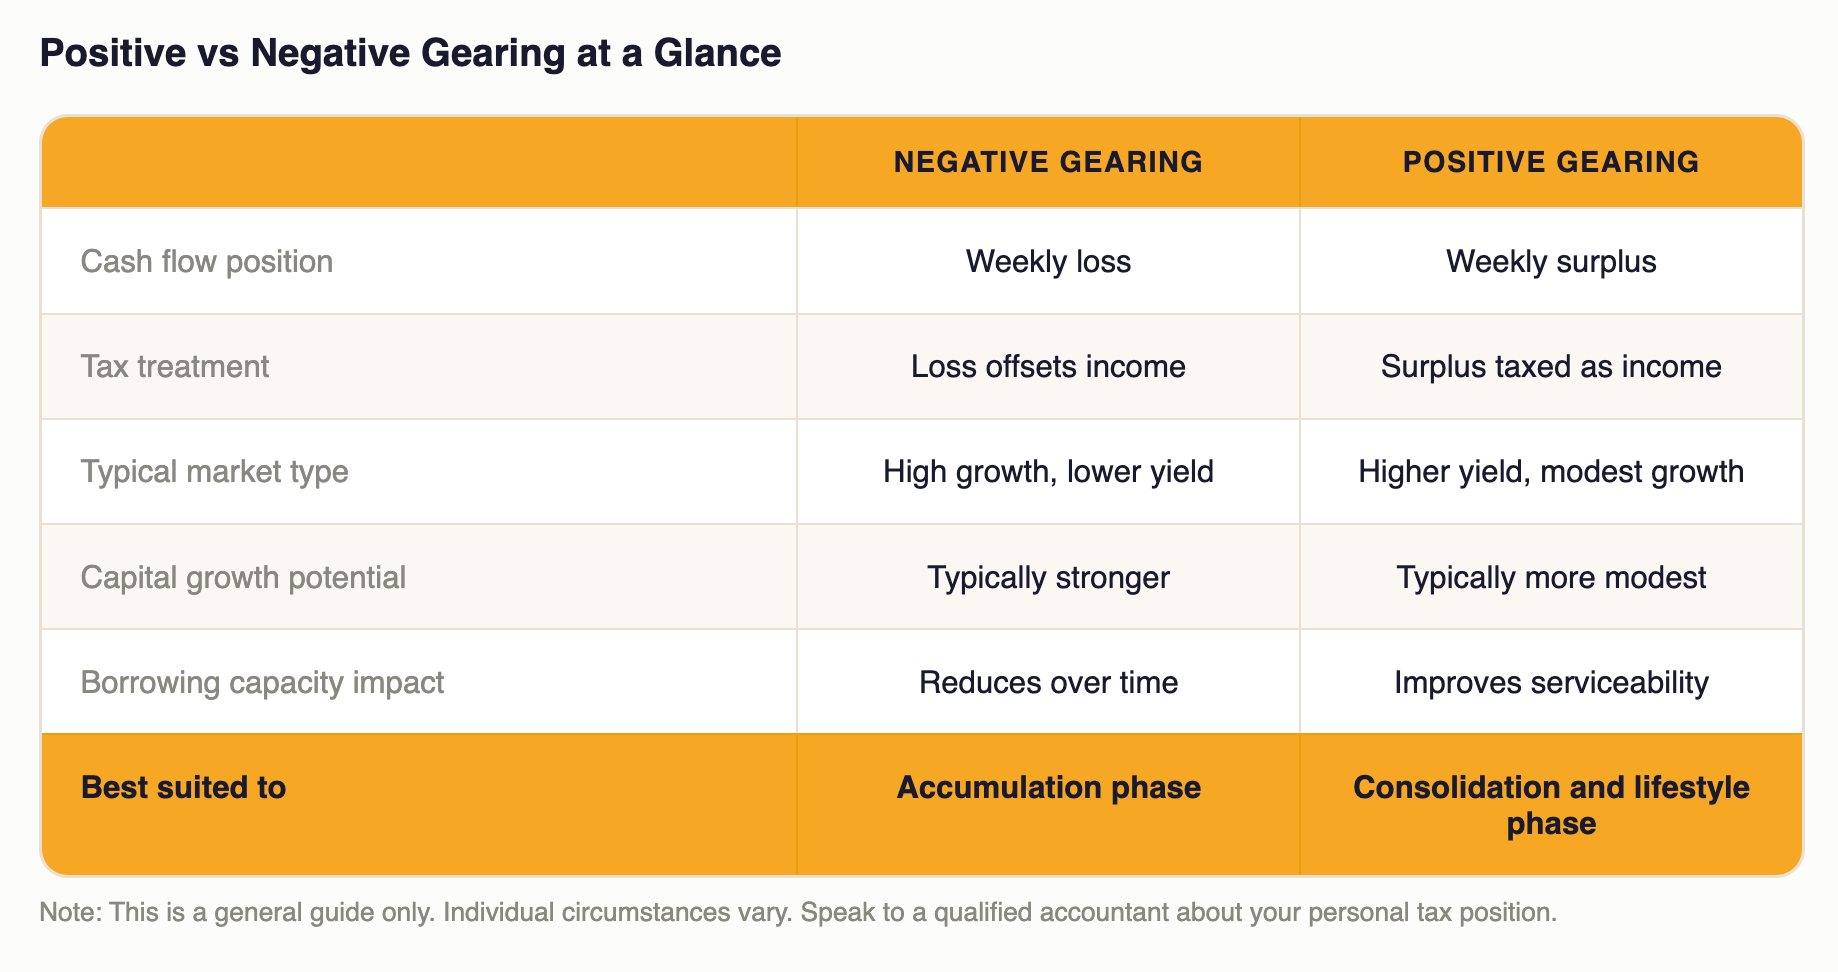
Positive gearing puts money in your pocket. Negative gearing takes it out. Most investors treat these as opposing camps and pick a side. The investors who actually build wealth understand both and use them deliberately.
Knowing when each one is appropriate and how they interact with your broader portfolio strategy is what separates investors who keep building from those who stall after one or two properties.
Negative gearing occurs when your property's holding costs exceed the rental income it generates. The difference is a loss that, under the rules that applied before the 2026 budget, could be offset against your wages and salary income in the year it occurred.
For established residential properties purchased after 12 May 2026, that loss now carries forward against future property income rather than being immediately deductible against wages. For properties purchased before that date, full negative gearing is grandfathered. New builds and off-the-plan apartments retain full negative gearing under the new rules. For a full breakdown of how the changes work, read our blog: What Does the 2026 Budget Mean for Australian Property Prices and Rents.
The key point most investors miss is that negative gearing is not a strategy in itself. It is a byproduct of holding a high-growth asset that has not yet generated enough rental income to cover its costs. The tax benefit is a bonus, not the reason to buy.
What Is Positive Gearing?
Positive gearing occurs when rental income exceeds all holding costs. The surplus is added to your taxable income and taxed at your marginal rate.
Example:
Weekly rent: $600
Weekly holding costs: $480
Weekly surplus: $120 positively geared
Positively geared properties improve your borrowing capacity because lenders factor the surplus rental income into their serviceability assessments. They reduce financial stress because the property covers its own costs. They also allow investors to hold more assets simultaneously without the same drain on personal income.
The trade-off is that positively geared properties are most commonly found in markets with lower median prices and historically lower capital growth rates than negatively geared assets in major capital cities.
Cash Flow vs Capital Growth: The Real Trade-Off
The real debate in property investing is not positive versus negative gearing. It is cash flow versus capital growth.
High-yielding positively geared properties tend to be found in regional markets, outer suburbs, and lower-median-price areas where rental income is strong relative to the purchase price. These markets have historically delivered more modest capital growth than well-located capital city or inner suburban assets.
High-growth assets in supply-constrained markets tend to start negatively geared because the entry price is higher relative to rental income. Over time, as rents rise and the mortgage balance reduces, the cash flow position improves. Many properties that start negatively geared in year one are approaching neutral or positive by year ten.
Consider two properties both purchased at $600,000:
Property A generates $520 per week in rent and grows at 3% annually. Annual capital growth: $18,000.
Property B generates $380 per week in rent and grows at 7% annually. Annual capital growth: $42,000.
Property A puts more money in your pocket each week. Property B puts $24,000 more into your net worth each year. Over a 15-year hold period, that gap compounds into a fundamentally different financial outcome.
Rental income is taxed as ordinary income each year. Capital growth is not taxed until you sell and at a reduced rate if held longer than 12 months. This tax deferral allows capital growth to compound more efficiently than income over long hold periods.
How Each Type Fits Into a Portfolio Strategy
The most effective property portfolios are not exclusively positive or negative. They are built with intention across different financial goals.
A deeply negatively geared portfolio with no positive cash flow buffer is fragile. One rate rise or extended vacancy period can force a sale at the wrong time. A purely positively geared portfolio in low-growth markets may feel comfortable but rarely builds the asset base required for genuine financial independence.
The investors who build serious wealth through property use both. High-growth assets in supply-constrained markets do the compounding. Higher-yielding assets provide the cash flow buffer that allows the portfolio to keep growing without becoming a financial burden. Getting the balance right for your specific income, borrowing capacity, and goals is what determines how far the portfolio can go.
Tax Implications in Plain Terms
Negatively geared properties produce a loss that currently carries forward against future property income for new established purchases after 12 May 2026. For grandfathered properties, losses continue to offset wages immediately. Either way the tax benefit is real, it is just a question of timing.
Positively geared properties add rental profit to your taxable income. At a 37% marginal rate, a property generating $10,000 in annual surplus adds approximately $3,700 to your tax bill. The property still nets you $6,300 after tax in addition to any capital growth. You are still ahead.
The golden rule remains unchanged by the budget: do not buy property primarily for tax benefits. A property that does not grow is not a wealth-building asset regardless of its tax treatment. A property that grows and generates rising rental income performs regardless of what the tax rules say.
Which One Is Right for You?
The answer depends on where you are in your investment journey, your income, your borrowing capacity, and your goals.
Negative gearing makes more sense when:
You are prioritising long-term capital growth
You have sufficient income to service the shortfall comfortably
You are buying in a supply-constrained market with genuine long-term demand drivers
The asset has strong capital growth potential that justifies the holding cost
Positive gearing makes more sense when:
You are prioritising income and cash flow stability
Your borrowing capacity is constrained and you need rental income to service future purchases
You want to reduce financial pressure across a growing portfolio
You are adding yield to balance a portfolio already weighted toward growth assets
Most serious investors hold both at different points in their portfolio's development. The sequencing matters more than the preference.
Ready to Build a Portfolio That Uses Both Strategies at the Right Time?
At Search Property, we help Australians cut through the noise and build data-driven investment strategies aligned with long-term wealth goals. Our buyers agents have helped thousands of clients build wealth through property because we focus on fundamentals, not headlines.
Book an investment assessment call with Search Property. We'll discuss your goals and position, and help you build a clear plan to move forward with confidence.
Frequently Asked Questions
Has the 2026 budget made negative gearing redundant?
No. For grandfathered properties it continues to work exactly as before. For new established purchases, losses carry forward rather than being immediately deductible. The capital growth case for quality assets in supply-constrained markets is unchanged. New builds retain full negative gearing
Which generates more wealth over time: positive or negative gearing?
Historically, negative gearing on high-growth assets in supply-constrained markets has produced stronger long-term wealth outcomes than positive gearing on high-yield assets in lower-growth markets. The compounding advantage of capital growth over long hold periods significantly outweighs the annual income advantage of positive gearing in most scenarios.
Can a property start negatively geared and become positively geared?
Yes. As rents rise over time and the mortgage balance reduces through repayments, the cash flow position improves. A property running at a $150 per week deficit in year one may be cash flow neutral by year eight and positively geared by year twelve depending on rental growth and interest rate movements.
Does positive gearing hurt my tax position?
It adds to your taxable income but that is not the same as hurting your position. A positively geared property generating $10,000 in annual surplus adds approximately $3,700 in tax at a 37% marginal rate. You still net $6,300 after tax plus any capital growth.
How do I know which strategy is right for my situation?
It depends on your income, borrowing capacity, and goals. Investors prioritising capital growth typically benefit from negatively geared assets in supply-constrained markets. Investors prioritising cash flow and stability typically benefit from positively geared assets. Getting the balance right is where professional guidance makes the most significant difference.
Disclaimer: Important Notice for Readers
By reading the content provided on this blog, you acknowledge and agree to the terms outlined in this disclaimer, binding yourself to its provisions unconditionally.
This blog presents information for informational, educational, and general non-advisory purposes only. It's important for you, the reader, to understand that the information provided does not take into account your specific personal, financial, or other circumstances. Consequently, we do not offer legal, financial, investment, or taxation advice, recommendations, or guidance. Before acting upon any information from this blog, you are strongly advised to consult with an independent professional, including legal, financial, taxation, accounting, or other relevant advisors, to verify the information’s relevance to your particular situation.
The information is provided in good faith, derived from sources believed to be reliable. However, we do not guarantee the accuracy, completeness, or applicability of the information to your individual circumstances, needs, objectives, or financial situation. The information may be selective and has not been independently verified. Therefore, it should not be the sole basis for any decision-making.
We expressly disclaim any liability for errors, omissions, or inaccuracies in the information, as well as any direct or indirect losses, damages, or expenses that arise from relying on our content, regardless of the cause, including negligence or other factors. Your engagement with this blog is entirely at your own risk.
Please be aware, we do not hold an Australian Financial Services Licence as defined by section 9 of the Corporations Act 2001 (Cth), nor are we authorised to provide financial services, and we have not provided financial services to you.
Disclaimer: Search Property Pty Ltd (SP) does not provide financial or investment advice and does not hold a financial services license as defined in the Corporations Act 2001 (Cth). Any advice given by SP is general in nature and does not take into account your personal circumstances or objectives, financial situation or needs.